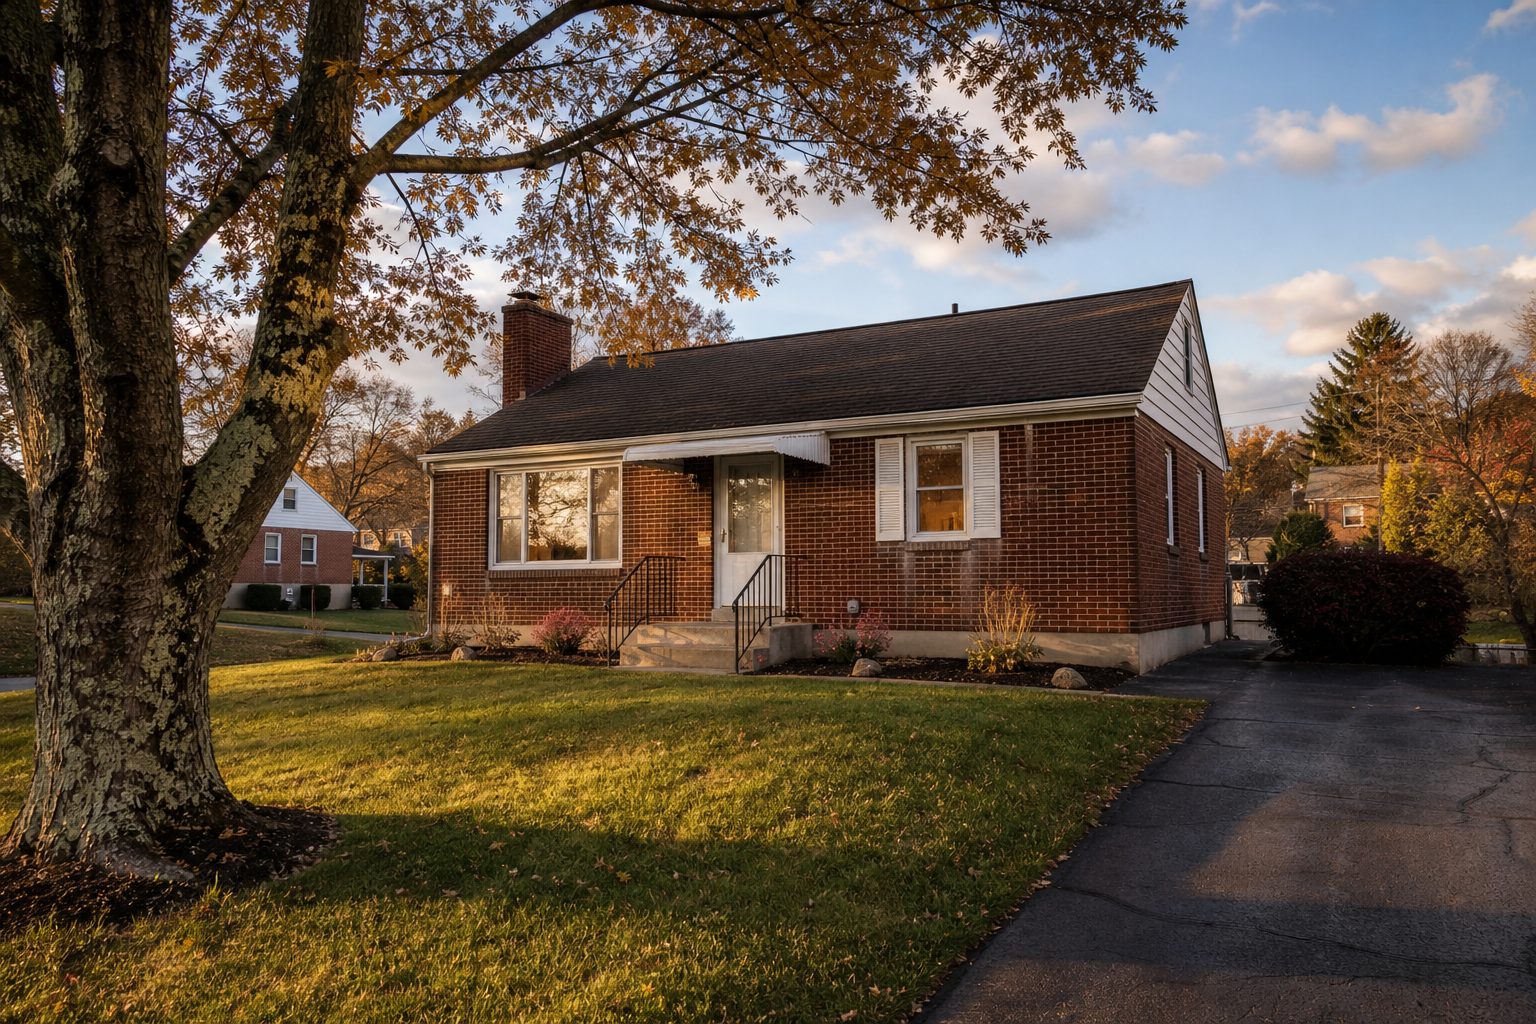
What first-time homebuyer programs does PHFA offer in 2026, and how can Penn Hills buyers use them?
PHFA offers forgivable loans, zero-interest assistance, and grants that can cover your down payment and closing costs on a Penn Hills home, often totaling $10,000 to $16,000 in stacked assistance.
Why This Matters Right Now for Penn Hills First-Time Buyers
I’m Mike Pastor, and I lead the Mike Pastor Group here in Pittsburgh. Over 12 years and more than 850 closed transactions, I’ve watched one pattern repeat itself constantly: buyers with solid paychecks walk away from homeownership because they think they don’t have enough cash saved. Most of them never even ask about down payment assistance. That’s the part that keeps me up at night.
Penn Hills is one of the most accessible entry points in the entire Pittsburgh metro. Median home prices range from $185,000 to $320,000 in 2026, according to West Penn MLS and Allegheny County records. That’s roughly half of Pennsylvania’s statewide median sale price of $338,939, per June 2026 data. When you layer PHFA assistance on top of those prices, the math changes dramatically. You could be looking at a home along Rodi Road or one of the quieter streets off Lime Hollow Road for less out of pocket than most people realize.
How PHFA’s Keystone Home Loan Works for Pittsburgh Buyers
The Keystone Home Loan is PHFA’s flagship first mortgage program, and it’s the foundation you’ll build everything else on. Think of it as the main loan that finances your purchase. It can be structured as a conventional, FHA, VA, or USDA loan. What makes it different is the layer of PHFA benefits wrapped around it, including access to every down payment assistance program I’m about to walk you through.
Here’s what you need to know about eligibility, per PHFA’s official home purchase programs:
- First-time buyer requirement: You (and all adults who will live in the home within 12 months of closing) cannot have had an ownership interest in a principal residence during the previous three years
- Maximum loan amount: $806,500
- Credit score note: If your middle credit score falls below 680, you’ll need to complete a homebuyer education class through a PHFA-approved counseling organization before closing
- Veterans exception: If you’re a discharged veteran of the U.S. Armed Forces, the first-time buyer requirement is waived
One thing I always tell my buyers: getting approved for a Keystone Home Loan isn’t something you do with just any lender. You need a PHFA-approved lender who processes these loans regularly. I connect buyers with lenders who run these programs every week, so your offer stays strong and your timeline doesn’t slip.
K-FIT: The Most Generous Down Payment Assistance in Penn Hills
If there’s one program I wish every first-time homebuyer in Pittsburgh knew about, it’s K-FIT, which stands for Keystone Forgivable in Ten Years. This is the program that changes the entire equation.
K-FIT provides 5% of the purchase price or appraised value (whichever is less) as a forgivable second mortgage. There’s no monthly payment on it. It forgives at a rate of 10% per year. Stay in your home for ten years, and you owe nothing.
Let me put that into Penn Hills terms. Homes in Penn Hills sold for a median price of $194,000 in May 2026, according to market data. At that price point, K-FIT would provide approximately $9,700 toward your down payment and closing costs. On a home at the higher end of Penn Hills pricing, say $255,000 (which is Pittsburgh’s citywide median, per October 2026 data across 1,660 closings), you’d receive approximately $12,750.
That’s real money. And for a buyer with steady income who’s been putting off homeownership because of savings, it can be the difference between renting on Frankstown Road and owning on one of those generous lots off Universal Road.
K-FIT Eligibility Requirements
- Minimum credit score of 660
- Liquid assets cannot exceed $50,000 after closing costs
- Home must be your primary residence in Pennsylvania
- Homebuyer education course required
- Must qualify for a PHFA first mortgage (Keystone Home Loan)
The catch? If you sell, refinance, or move out before the ten years are up, you may need to repay the remaining unforgiven balance. K-FIT rewards buyers who plan to put down roots, and Penn Hills is exactly the kind of community where that makes sense.
Keystone Advantage and HOMEstead: Stacking Your Pittsburgh Assistance
Here’s where it gets interesting. PHFA doesn’t limit you to just one assistance program. You can stack multiple programs together to maximize your total help.
Keystone Advantage Assistance Loan
This program provides up to 4% of the loan amount or $6,000, whichever is less, per PHFA’s official Seller’s Guide. It’s a 0% interest second mortgage that amortizes over ten years with a real monthly payment. It is not forgivable and not deferred, so understand that distinction clearly.
You’ll need to contribute the lesser of $1,000 or 1% from your own funds, a minimum credit score of 660, and liquid assets of $50,000 or less.
HOMEstead Down Payment Assistance
The HOMEstead program offers up to $10,000 as a forgivable loan that forgives at 20% per year over five years of owner-occupancy. That’s a faster forgiveness schedule than K-FIT. The trade-off is stricter income limits: you need to be at or below 80% of the area median income. Pittsburgh is listed as one of the cities where this program is available, per PHFA’s assistance programs.
One important restriction: most homes built before 1978 are not eligible for HOMEstead. Given that Penn Hills has a mix of housing stock from the mid-twentieth century through newer construction, you’ll want your lender to verify eligibility for any specific property.
Maximum Stacked Assistance
According to PHFA program guidelines, you can potentially stack $10,000 in forgivable HOMEstead assistance plus $6,000 from Keystone Advantage for a combined $16,000 in total down payment and closing cost help.
What does that actually look like for your wallet? On a $194,000 Penn Hills home, $16,000 in assistance could cover your entire FHA down payment (3.5% would be roughly $6,790) plus a significant portion of your closing costs.
The PHFA Grant and K-DATE: Two More Pittsburgh Options Worth Knowing
PHFA Grant ($500)
This is a straightforward, no-repayment-required $500 grant toward down payment and closing costs. It’s available to buyers using the HFA Preferred (Lo MI) loan through PHFA. Five hundred dollars might sound modest, but when you’re stretching every dollar to get to the closing table, it matters.
K-DATE (Keystone Deferred Assistance)
K-DATE is part of PHFA’s Keystone Flex program. It provides a 0% interest second mortgage of 5% for loans above $150,000, or 8% for loans of $150,000 or less. Repayment is deferred entirely until you sell, refinance, or pay off your first mortgage.
For a buyer eyeing one of the smaller starter homes in Penn Hills that trade below $150,000 (and they do exist along parts of Frankstown Road), K-DATE at the 8% level could be substantial.
Why Penn Hills Is the Right Fit for PHFA-Assisted Buyers
So why do I keep pointing first-time buyers toward Penn Hills specifically? Because the numbers align better here than almost anywhere else in the metro.
Properties in Penn Hills are selling after just 10 days on market in May 2026, down from 12 days the previous year. That tells you demand is healthy, which is important for your long-term equity. But with median prices sitting well below Pittsburgh’s citywide median of $255,000 (as of October 2026) and far below the statewide median, your PHFA assistance goes further here.
You get access to Penn Hills Community Park on Rodi Road, Renzie Park with its walking paths and picnic pavilions, and you’re under 10 minutes from Monroeville-area employers. The 61A, 61B, and 61C bus routes connect you to Downtown Pittsburgh along Penn Avenue, and the drive is approximately 25 to 35 minutes via I-376 West. Penn Hills is a community of brick ranches, split-levels, generous lots, and neighbors who’ve stayed for decades. It’s exactly the kind of place where a 10-year forgivable loan makes perfect sense because you’re going to want to stay.
Having closed over 850 transactions in the Pittsburgh market and earning recognition as a top Pittsburgh real estate agent, I can tell you that down payment help is real, and most first-time buyers never ask about it. These PHFA programs come with income limits, specific rules, and a lender who knows them inside and out. That last part is non-negotiable.
Frequently Asked Questions About PHFA Programs in Penn Hills and Pittsburgh
What is the minimum credit score for PHFA programs?
The minimum credit score is 660 for most PHFA programs, including K-FIT and Keystone Advantage, per PHFA’s official Seller’s Guide (August 2026). If your score falls below 680, you’ll also need to complete a homebuyer education class through a PHFA-approved counseling organization before closing. This requirement applies across all PHFA-supported loan types.
Do I have to be a first-time homebuyer to use PHFA programs?
For the Keystone Home Loan, yes. PHFA defines “first-time buyer” as someone who has not had an ownership interest in a principal residence during the previous three years. However, veterans discharged from the U.S. Armed Forces and buyers purchasing in designated “targeted” counties or areas can qualify even if they’ve owned before.
How much down payment assistance can I get through K-FIT?
K-FIT provides 5% of the purchase price or appraised value, whichever is less, with no dollar cap, per PHFA guidelines. On a Penn Hills home at the May 2026 median of $194,000, that comes to approximately $9,700. The loan forgives at 10% per year over ten years with no monthly payment required.
Can I combine multiple PHFA assistance programs?
Yes. According to PHFA program guidelines, you can stack programs such as the $10,000 forgivable HOMEstead loan and the $6,000 Keystone Advantage loan for up to $16,000 in total assistance. Eligibility for each program must be confirmed separately through your PHFA-approved lender.
What are the income limits for PHFA’s HOMEstead program?
Your household income must be at or below 80% of the area median income (AMI), and limits vary by county, per PHFA program documentation. Your PHFA-approved lender will verify whether your income qualifies based on current Allegheny County limits.
Is the Keystone Advantage loan forgivable?
No. The Keystone Advantage Assistance Loan is not forgivable, per PHFA’s official Seller’s Guide. It is a 0% interest second mortgage capped at $6,000 or 4% of the loan amount (whichever is less) that you repay over a ten-year amortization schedule with real monthly payments.
Do I need to take a homebuyer education course?
If your credit score is below 680, PHFA requires you to complete a homebuyer education class from a PHFA-approved counseling organization before closing. K-FIT also requires homebuyer education regardless of credit score, per PHFA eligibility guidelines. Many of these courses are available online and can be completed in a few hours.
Can I use PHFA programs on any home in Penn Hills?
Most homes qualify, but there are exceptions. The HOMEstead program, for example, generally excludes homes built prior to 1978, per program guidelines. The Keystone Home Loan has a maximum loan amount of $806,500 (per the August 2026 Seller’s Guide), which is well above Penn Hills price points. Your lender will confirm property eligibility during the application process.
What happens if I sell my Penn Hills home before K-FIT is fully forgiven?
If you sell, refinance, or move out before the ten-year forgiveness period is complete, you may need to repay the remaining unforgiven balance of your K-FIT loan, per PHFA guidelines. For example, if you sell after six years, 60% of the loan would be forgiven and you’d repay the remaining 40%.
How long does the PHFA loan approval process take?
The timeline depends on your lender, but working with a PHFA-approved lender who processes these loans regularly keeps things on schedule. I connect my buyers with lenders who handle PHFA programs every week, which is critical because a lender unfamiliar with the process can cause delays that cost you a property, especially in Penn Hills where homes are selling in about 10 days on market (as of May 2026).
The Bottom Line
You don’t need a trust fund to buy a home in Penn Hills. You need steady income, a credit score of 660 or better, and the right team guiding you through PHFA’s programs. Between K-FIT, Keystone Advantage, HOMEstead, and the PHFA Grant, you could be looking at $10,000 to $16,000 in assistance on a home that’s already priced well below the state and national medians.
I’m Mike Pastor with the Mike Pastor Group at Realty ONE Group Landmark, and with 120 five-star reviews from past clients and over 850 closed transactions across the Pittsburgh market, first-time buyer education is something I take personally. If you’re ready to find out what you qualify for, give me a call at 412-214-9494 or visit my team online at pittsburghhometeam.com. I’ll connect you with a PHFA-approved lender, walk you through the numbers, and help you find your place in Penn Hills.